

How to File a Roof Insurance Claim in California
Protect the roof, document the damage and tell your insurer without delay. California's standard fire policy terms require you to give written notice of a loss without unnecessary delay, protect the property from further damage, and send a sworn proof of loss within 60 days after the loss unless the insurer extends that in writing (Insurance Code 2071); after a declared state of emergency, the insurer can't require it sooner than 100 days after the loss (2051.5). The insurer then has its own clock: within 15 calendar days of your notice it has to acknowledge the claim, send you the forms and instructions, and start investigating, and within 40 calendar days of your proof of claim it has to accept or deny it, in writing with its reasons if it denies (California Code of Regulations, title 10, sections 2695.5 and 2695.7). Whether the damage is covered at all depends on the cause; a worn-out roof generally isn't. This page explains the process; it isn't legal advice about a particular claim.
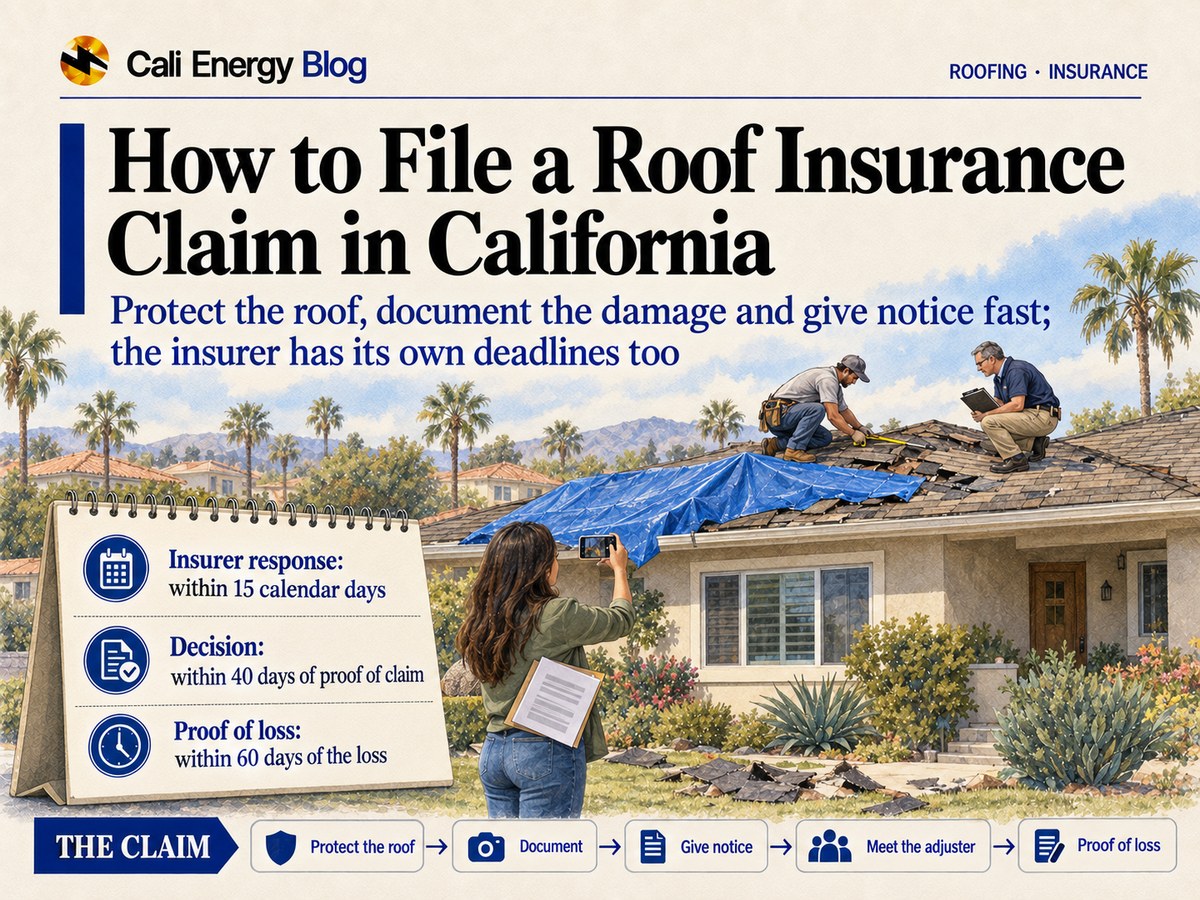
The steps, in order
1. Protect the roof from further damage. The policy terms require it. On a roof, that can mean a tarp or plastic sheeting over an opening and drying out what got wet. The Department of Insurance's claims guide says your insurer reimburses reasonable costs to protect the property if you keep the receipts, and not to make extensive permanent repairs until the adjuster has assessed the damage. What to do while water is still coming in is in emergency roof leak in a storm.
- Document everything. Photos and video of the roof from the ground, the attic and any ceiling or wall damage, with the date of the event. Keep the damaged materials, or photos of them, until the insurer has seen them: the policy lets the insurer ask to see what remains of the damaged property.
- Give notice. Report the loss to the insurer in writing, get a claim number, and keep a log of every call, email and visit.
- Get a roofer's inspection. A written report with photos and a scope of the repair or replacement gives you something to compare with the adjuster's estimate; what a useful report covers is in what a roof inspection checks.
- Meet the adjuster. Be there, or have your roofer there, when the adjuster inspects, and ask for the estimate in writing.
- Send the proof of loss. It's a signed, sworn statement of the loss; the insurer has to give you the forms and tell you what it needs.
- Follow the decision and the payments, using the deadlines below.
The claim clock
The deadlines come from the standard policy terms, the claims regulations and the replacement cost statute.
| Step | Deadline | Source |
|---|---|---|
| You give notice | Without unnecessary delay | Insurance Code 2071 |
| The insurer acknowledges, sends forms and instructions, starts investigating | Within 15 calendar days of your notice | 10 CCR 2695.5(e) |
| You send the proof of loss | Within 60 days after the loss, unless the insurer extends it in writing; after a declared state of emergency, not required sooner than 100 days, with three-month extensions for good cause | Insurance Code 2071, 2051.5(b)(3) |
| The insurer accepts or denies | Within 40 calendar days of your proof of claim; if it needs more time, a written notice saying why, then every 30 days | 10 CCR 2695.7(b), (c)(1) |
| The insurer pays what it accepted | Within 30 calendar days of accepting | 10 CCR 2695.7(h) |
| You collect full replacement cost | At least 12 months from the first actual cash value payment; at least 36 months for a loss tied to a state of emergency | Insurance Code 2051.5(b)(1) |
| A lawsuit on the policy | Within 12 months after the loss; 24 months for a loss tied to a state of emergency | Insurance Code 2071 |
Policies can give you more time than these minimums. A replacement cost policy can pay the actual cash value first and the rest after the work is done, which is why the replacement cost window matters; what to expect from that payment is in does insurance cover a roof replacement?.
If you disagree
- Ask for the reasons in writing. A denial, in whole or in part, has to be written and list every basis for it, with the facts and law behind each (10 CCR 2695.7(b)(1)).
- Use appraisal for disputes about the amount. If you and the insurer disagree about the actual cash value or the amount of the loss, either side can request appraisal in writing; each picks a disinterested appraiser, and an umpire settles what they can't agree on (Insurance Code 2071).
- Call the Department of Insurance. The California Department of Insurance takes questions at 1-800-927-4357 and accepts complaints about claims online.
- Talk to a lawyer about coverage disputes, and mind the lawsuit deadline above.
Claims with their own rules
Some losses add steps. Smoke and ash damage from a wildfire falls under a new law for claims from January 1, 2027, covered in roof damage after a nearby wildfire. A roof that simply wore out, leaked through old underlayment or was neglected generally isn't covered, as laid out in does insurance cover a roof replacement?, and how your insurer treats the roof's age is in roof age and home insurance.
Frequently asked
How long do I have to file a roof insurance claim in California?
How long does the insurer have to respond?
Can I tarp the roof before the adjuster comes?
Should I get my own roofer's estimate?
What can I do if the claim is denied?
Related reading
Sources & methodology
Code sections, rules and figures on this page come from the primary sources below. Codes, local requirements and product terms change; each was verified October 8, 2026.
- California Insurance Code §2071 (standard form fire policy: requirements in case loss occurs, appraisal, suit)
- California Department of Insurance, Residential Property Claims Guide (updated February 27, 2025)
- California Insurance Code §2051.5 (time to collect replacement cost; proof of loss after a state of emergency)
- California Code of Regulations, title 10, §2695.5 (duties upon receipt of communications)
- California Code of Regulations, title 10, §2695.7 (standards for prompt, fair and equitable settlements)
- California Department of Insurance, Fair Claims Settlement Practices Regulations
- California Department of Insurance, Getting Help
We inspect the damage and put it in writing for your claim
Call (323) 844-7777. We inspect the roof and attic, photograph the damage, protect the roof if it's open, and write up what the repair or replacement involves, so you can give your insurer a clear record. Have ready your claim number, if you have one, and the date of the damage.
Prepared by Cali Energy, October 8, 2026. This article is for general educational purposes only and is not legal, tax, financial, engineering, or utility advice. Rates, incentives, codes, permit requirements, equipment specifications, prices, and program terms may change; figures and timelines are estimates, not guarantees. Confirm current requirements with the applicable utility, AHJ, program administrator, manufacturer, or a licensed professional. See our Content Disclaimer. Cali Energy · 19201 Parthenia St, Unit E, Northridge, CA 91324 · CSLB #1032379 (B, C-10, C-39)